New York startups raised $3.14B across 59 rounds in September 2026, up 274% from August and 49% above September 2025. The rebound came from the top. Ten rounds of $100M or more accounted for $2.17B, or 69% of the month, with Cyera’s $400M leading the list. Deal count recovered from August’s 34 rounds but remains 38% below the 95 rounds recorded a year ago, which pushed the average round to $53.2M. New York took 10.8% of US venture capital in September, up from 4.8% in August, as national funding fell 5.8% from a year ago.
- Ten rounds of $100M or more in September, against one in August, when Cityblock Health’s $116M was the largest. Those ten took 69% of the month’s capital.
- Series B capital reached $771.0M across 9 rounds, up from $100.0M across 3 in August. David ($250M) and General Intuition ($220M) led, and New York captured 23.2% of all US Series B capital.
- Series A rounds jumped from 5 to 13 and capital grew from $51.6M to $310.1M, roughly six times August’s total.
- Fewer, larger rounds than a year ago. Capital is up 49% from September 2025 on 38% fewer rounds, and the average round is more than double last September’s.
- New York outpaced the nation. US capital fell 5.8% from September 2025, lifting New York to 10.8% of US capital from 4.8% in August.
- Repeat backers at the top. Andreessen Horowitz invested in four September rounds (EliseAI, Clay, Highstock, Adaptive Real Estate). Thrive Capital and Khosla Ventures each backed three of the ten largest rounds.
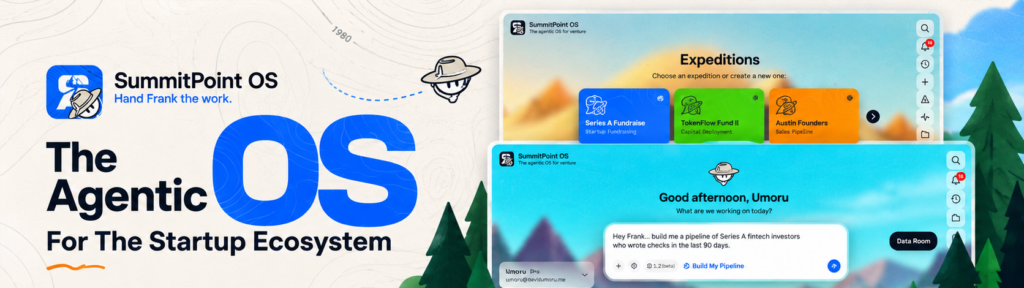
SummitPoint OS is the operating system for venture, guided by Frank. Hand him the work.
Venture runs on databases you search and spreadsheets you maintain. SummitPoint OS is one workspace for founders, investors and Industry Partners, and Frank, SummitPoint’s agentic AI analyst, does the work: builds the investor pipeline and writes the briefing on every name, screens the inbound deal against your thesis, watches every founder in your program, and shows you what he did.
Trailing 12 Months
| Month | Capital Raised | Rounds |
|---|---|---|
| Oct 2025 | $1.40B | 75 |
| Nov 2025 | $1.30B | 51 |
| Dec 2025 | $2.00B | 74 |
| Jan 2026 | $1.30B | 78 |
| Feb 2026 | $2.50B | 75 |
| Mar 2026 | $3.70B | 94 |
| Apr 2026 | $1.90B | 73 |
| May 2026 | $2.30B | 80 |
| Jun 2026 | $3.90B | 68 |
| Jul 2026 | $1.81B | 53 |
| Aug 2026 | $837.9M | 34 |
| Sep 2026 | $3.14B | 59 |
September ranks as the third-largest month of the past twelve, behind June and March.
Stage Breakdown
| Stage | Rounds | Capital | Share | Avg Round | Aug Rounds / Capital |
|---|---|---|---|---|---|
| Late-Stage | 11 | $1.87B | 59.6% | $169.8M | 11 / $597.7M |
| Series B | 9 | $771.0M | 24.6% | $85.7M | 3 / $100.0M |
| Series A | 13 | $310.1M | 9.9% | $23.9M | 5 / $51.6M |
| Early-Stage | 26 | $187.1M | 6.0% | $7.2M | 15 / $92.3M |
| Total | 59 | $3.14B | 100.0% | $53.2M | 34 / $837.9M |
Top 10 Rounds
| # | Company | Amount | Stage | Investors |
|---|---|---|---|---|
| 1 | Cyera AI-native data security platform |
$400.0M | Late-Stage | Goldman Sachs Growth Equity |
| 2 | EliseAI AI automation for housing and healthcare |
$350.0M | Late-Stage | Ontario Teachers’ Pension Plan, Bessemer Venture Partners, Andreessen Horowitz |
| 3 | Precision Neuroscience Brain-computer interfaces |
$250.0M | Late-Stage | ARK Investment Management, Korea Investment Partners, Ackman Oxman Institute |
| 4 | David Food and beverage brand (Medici Brands) |
$250.0M | Series B | Valor Equity Partners, Imaginary Ventures, ICONIQ Capital |
| 5 | General Intuition AI research lab learning through play |
$220.0M | Series B | Valor Equity Partners, Atreides Management, General Catalyst |
| 6 | Profound AI visibility for brands |
$180.0M | Late-Stage | Lightspeed Venture Partners, Sequoia Capital, Kleiner Perkins |
| 7 | Rightway Health benefits technology |
$155.0M | Late-Stage | Francisco Partners, Khosla Ventures, Thrive Capital |
| 8 | Forus AI medication access platform |
$150.0M | Late-Stage | Bain Capital Ventures, General Catalyst, Thrive Capital |
| 9 | Clay AI go-to-market platform |
$115.0M | Late-Stage | Evolution Equity Partners, Wellington Management, Andreessen Horowitz |
| 10 | Savvy Wealth Digital wealth management |
$100.0M | Late-Stage | Industry Ventures from Goldman Sachs, Euclidean Capital, Vestigo Ventures |
The Month in Detail
Late-Stage: 11 rounds, $1.87B
Late-Stage rounds took 59.6% of September capital, more than three times August’s $597.7M. Cyera’s $400M Series G from Goldman Sachs Growth Equity was the largest round of the month, followed by EliseAI’s $350M. Health was the deepest vein: Precision Neuroscience ($250M Series D), Rightway ($155M Series E), Forus ($150M Series C) and Inspiren ($70M Series C) together raised $625M. Profound ($180M Series D, Lightspeed, Sequoia, Kleiner Perkins, Khosla), Clay ($115M Series D), Savvy Wealth ($100M Series C), Stuut ($67.6M) and Rogo ($30M) completed the group.
Series B: 9 rounds, $771.0M
David (Medici Brands) raised $250M from Valor Equity Partners, Imaginary Ventures, ICONIQ Capital and Greenoaks, and General Intuition, a research lab teaching machines to learn through play, raised $220M from Valor, Atreides, General Catalyst, Seven Seven Six, Khosla and Point72. Sequen followed with $90M led by Prysm Capital. Confido ($55M), Luzern Risk ($45M), Evvy ($40M), Adaptive Real Estate ($30M), Footprint ($25M) and Every Media ($16M) rounded out the stage.
Series A: 13 rounds, $310.1M
Ande led the stage with $52M in combined seed and Series A funding from Lightspeed, Redpoint, Duration and Sierra, with Bain Capital Ventures participating. HIFI raised $37M for stablecoin banking infrastructure, Antioch $32M for physical AI simulation software and Highstock $30M from Andreessen Horowitz and Greylock for a business-to-business manufacturer marketplace. Chamelio ($26M), OuterSignal ($22M), Luminary ($22M), Blee ($20M), Pave Finance ($15M), Aqua ($15M), UrgentIQ ($15M), Norbert Health ($14M) and Malayy ($10.1M) followed.
Early-Stage: 26 rounds, $187.1M
Early-Stage rounds were the most numerous but averaged just $7.2M. Fin.com and Polyphron each raised $20M. Midcentury ($15M) is building data and simulation infrastructure for physical AI, and Liquid Compute ($15M) is creating a regulated marketplace for AI computing power. Tare ($13.2M), Rebuild Technology ($13M), BoomerangHR ($12.7M), AlgoX2 ($10M) and Clarion ($10M) rounded out the largest, while Destro AI, Konko AI, A Vinyl Bar in Shibuya, Elio Mortgage, Notes.fm and F2 AI each raised between $5M and $8M.
NYC vs. US
| Metric | NYC | US | NYC Share |
|---|---|---|---|
| Capital Raised | $3.14B | $29.10B | 10.8% |
| Rounds | 59 | 762 | 7.7% |
| Average Round | $53.2M | $38.2M | |
| Change vs. Sep 2025 (capital) | +49% | -5.8% | |
| Change vs. Aug 2026 (capital) | +274% | +61% |
NYC vs. US by Stage
| Stage | NYC Rounds | US Rounds | NYC Share | NYC Capital | US Capital | NYC Share |
|---|---|---|---|---|---|---|
| Late-Stage | 11 | 71 | 15.5% | $1.87B | $20.02B | 9.3% |
| Series B | 9 | 54 | 16.7% | $771.0M | $3.32B | 23.2% |
| Series A | 13 | 121 | 10.7% | $310.1M | $3.72B | 8.3% |
| Early-Stage | 26 | 516 | 5.0% | $187.1M | $2.05B | 9.1% |
| Total | 59 | 762 | 7.7% | $3.14B | $29.10B | 10.8% |
SummitPoint OS is the operating system for venture, guided by Frank. Hand him the work.
Venture runs on databases you search and spreadsheets you maintain. SummitPoint OS is one workspace for founders, investors and Industry Partners, and Frank, SummitPoint’s agentic AI analyst, does the work: builds the investor pipeline and writes the briefing on every name, screens the inbound deal against your thesis, watches every founder in your program, and shows you what he did.
Looking Ahead
October is already running hot. Through October 22, the index shows about $3.78B across 41 rounds, led by Ramp’s $1.9B and Modal’s $750M, so the month is on pace to finish well above September. Those figures are preliminary and will change as more rounds are added. Explore every round at the NYC Venture Capital and Startup Funding Index.
Methodology
Figures come from AlleyWatch’s proprietary NYC funding index and cover venture rounds raised by New York companies. US figures come from AlleyWatch’s national funding dataset. Corporate rounds, private equity and debt are excluded from stage definitions. Stages are grouped as Early-Stage (Pre-Seed, Seed, Angel, Accelerator, Incubator), Series A, Series B and Late-Stage (Series C and later). Year-over-year and month-over-month comparisons use previously published AlleyWatch totals.
View the media kit or email sales@alleywatch.com