Mortgage lending has digitized one step at a time, yet closing a loan still depends on people chasing documents across inboxes, portals, and phone calls. The U.S. residential market holds roughly $13T in outstanding loans and originated about $2T in 2025, less than half the $4.5T peak of 2021, which leaves loan officers little room to spend hours on coordination instead of finding clients. Companies respond by adding layers of support staff, and those layers lock in fixed costs that hurt most when volume falls. Elio Mortgage takes a different route: it operates as a licensed mortgage company and builds its AI platform inside that operation, where engineers work beside loan officers on live loans. The platform connects a borrower’s financial information with each lender’s requirements, fills in applications from data already provided, and flags missing documents before they stall a file, while one loan officer guides the borrower through dozens of lenders from first call to closing. Through Elio Embedded, the same infrastructure serves as the mortgage arm for financial advisors, real estate agents, homebuilders, and single-family rental operators, and the company already works with about 40 loan officers across 22 states and about $200M in trailing 12-month origination volume.
AlleyWatch sat down with Elio Mortgage Cofounder and COO Arad Lev Ari to learn more about the business, its future plans, recent funding round, and much, much more…
Who were your investors and how much did you raise?
We raised $5.1M in pre-seed funding led by Motive Partners and Social Leverage, with participation from Jeff Horing, cofounder of Insight Partners, and other angel investors.
Tell us about the product or service that Elio Mortgage offers.
Elio is an AI-native mortgage company creating a new model for origination. We help borrowers find financing through access to dozens of lenders, with a loan officer guiding them through the process.
Behind that experience, we’re building technology to automate the operational work involved in getting a mortgage closed. This gives loan officers more time to advise clients, build relationships, and grow their businesses. Through Elio Embedded, we also serve as the mortgage arm for businesses such as financial advisory firms, real estate companies, and homebuilders.
What inspired the start of Elio Mortgage?
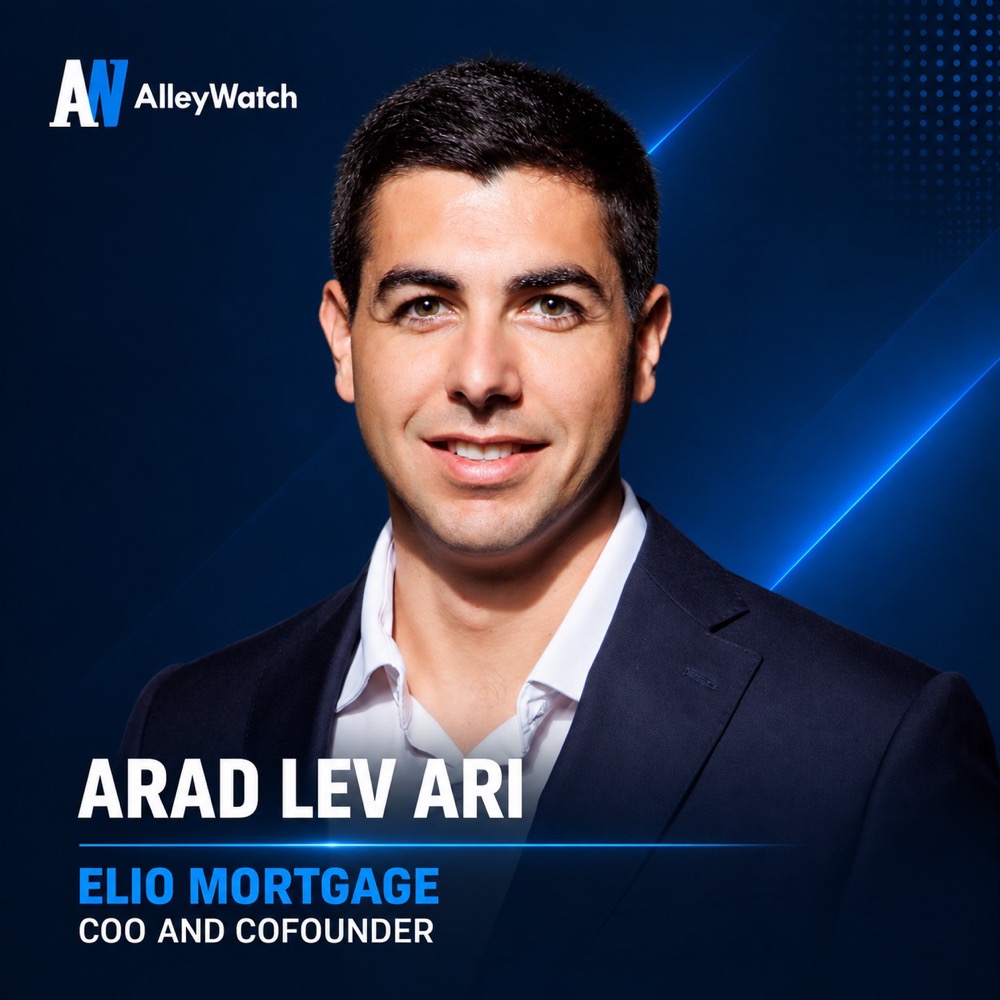 I started my career in investment banking at Deutsche Bank and then moved into real estate investing at KKR. One thing I kept seeing was how much work went into coordinating a transaction: information scattered across different systems, constant follow-ups, and many parties trying to keep everything moving.
We found the same problem in residential mortgages. Loan officers spend valuable time managing the process of getting loans closed, which limits their capacity to bring in business. Companies address that by adding layers of support staff, creating significant fixed costs.
My cofounder, Oren Michaely, brought experience from Microsoft and as Director of AI at Motive Partners. Together, we saw an opportunity to use AI to change how that work gets done.
How is Elio Mortgage different?
We’re building Elio around a simpler, more personalized mortgage experience. Our platform connects a borrower’s financial information with the requirements of different lenders and the steps needed to get a loan closed. It’s designed to fill in applications using information already provided, identify missing documents or potential problems early, and help loan officers find financing options that fit each borrower’s circumstances.
For borrowers, that means less repetition, fewer last-minute surprises, and clearer updates about what happens next. One loan officer guides them from the first conversation through closing, with more time to explain their options and offer advice. For loan officers, automating more of the paperwork and coordination creates room to serve more clients and grow their book of business.
We develop the technology inside our own mortgage business. Our engineers work alongside the people handling real loans, seeing where borrowers get frustrated, where files get delayed, and where human judgment is essential. That direct feedback helps us improve the technology and the mortgage experience together.
What market does Elio Mortgage target and how big is it?
We target the U.S. residential mortgage market, which has roughly $13 trillion in outstanding loans. Approximately $2 trillion of mortgages were originated in 2025. In 2021, when interest rates were much lower, annual originations exceeded $4.5 trillion, more than double that amount.
We serve both people buying a home and homeowners refinancing an existing mortgage. Home purchases generate demand as people become homeowners or move, while lower interest rates can drive substantial refinancing activity as borrowers look to reduce their borrowing costs. By year-end, we expect to be licensed in 30 states covering approximately 80% of the U.S. population.
What’s your business model?
We earn origination fees when a loan closes. Our business comes through two main channels: loan officers who bring clients through their relationships, and embedded partners whose customers need mortgage financing.
The economic opportunity is to increase the volume each loan officer can handle while reducing the operational cost of completing each loan. As we scale, we also see opportunities to participate in more of the lending process and capture more of the economics of each transaction.
How are you preparing for a potential economic slowdown?
Mortgage is a cyclical business, so building an efficient operating model is central to our strategy. We’re focused on reducing the manual work required to originate a loan and enabling growth without a proportional increase in support costs.
Our distribution strategy also builds on relationships that loan officers and partners already have with customers. The goal is a business that can operate efficiently across different market conditions and expand capacity as demand grows.
What was the funding process like?
The round was led by Motive Partners and Social Leverage, alongside a group of angel investors who bring deep experience across financial services and technology. The investment thesis centered on building an operating mortgage company with AI at its core and using that technology to change the economics of origination.
Having investors who understand financial services and the opportunity to build new business models around AI has been valuable as we develop the company.
What are the biggest challenges that you faced while raising capital?
One challenge was that Elio doesn’t fit the traditional software subscription model many venture investors are familiar with. We earn revenue by originating mortgages, so some questioned whether the business could deliver the growth and returns they look for in a venture investment. Others had been burned by previous investments in mortgage and were cautious given the number of software startups that have struggled in the industry.
That history helped shape our thesis, which is to build and operate a mortgage business with AI at its core, rather than sell software into the industry. This allows us to redesign how the work gets done and directly capture the benefits of a more efficient operation. Motive Partners, Social Leverage, and our other investors saw the opportunity in that approach.
What factors about your business led your investors to write the check?
Our investors have highlighted the combination of an AI-native operating model and embedded distribution. There is an opportunity to change the cost and complexity of originating a mortgage while reaching borrowers through businesses they already trust.
That creates two complementary opportunities: helping loan officers become more productive and enabling partners to offer mortgage services without building an entire mortgage operation themselves.
What are the milestones you plan to achieve in the next six months?
Our priorities are expanding our licensed footprint, growing loan officer count, and bringing more automation into the origination process. We’re currently licensed in 22 states and are targeting 30 by year-end.
Alongside that expansion, we want to demonstrate that the platform can support more loan volume without a proportional increase in operational costs. The focus is on growing the business while improving the economics and experience of each transaction.
What advice can you offer companies in New York that do not have a fresh injection of capital in the bank?
Make the most of being in New York. I think it’s the best place in the world to meet talented people across almost any industry, and so many of them are just a short commute away. That access is a real privilege.
Even before becoming a founder, I experienced this firsthand at Columbia, when I was networking to break into investment banking. Being able to meet people in person and build relationships made a real difference. For founders, I’d encourage the same approach: spend time with potential customers, learn from experienced operators, and build relationships before you need something. Those connections can help you win business and move forward with the resources you already have.
Where do you see the company going now over the near term?
We’re focused on scaling the origination business, supporting more loan officers, and developing our embedded partnerships. We already have approximately 40 loan officers across 22 states, and the next step is to build on that foundation while making the platform more effective.
Over time, we also see an opportunity to take on more of the lending process, including funding loans. That creates a path to growing both the volume we originate and the revenue we earn from each transaction.
What’s your favorite fall destination in and around the city?
It may be a little far from the city, but I’d say Art Omi in the Hudson Valley. My college friends and I used to go up every fall and stay at a friend’s house, and visiting Art Omi was part of the tradition. Unfortunately, they sold the house a couple of years ago, so I haven’t been back since, but I have great memories of those trips.